Fed December 25 bps hike odds stay elevated
Fed December 25 bps hike odds held near two-thirds on Polymarket after the tech rout, even as CME FedWatch cooled from late-September highs.
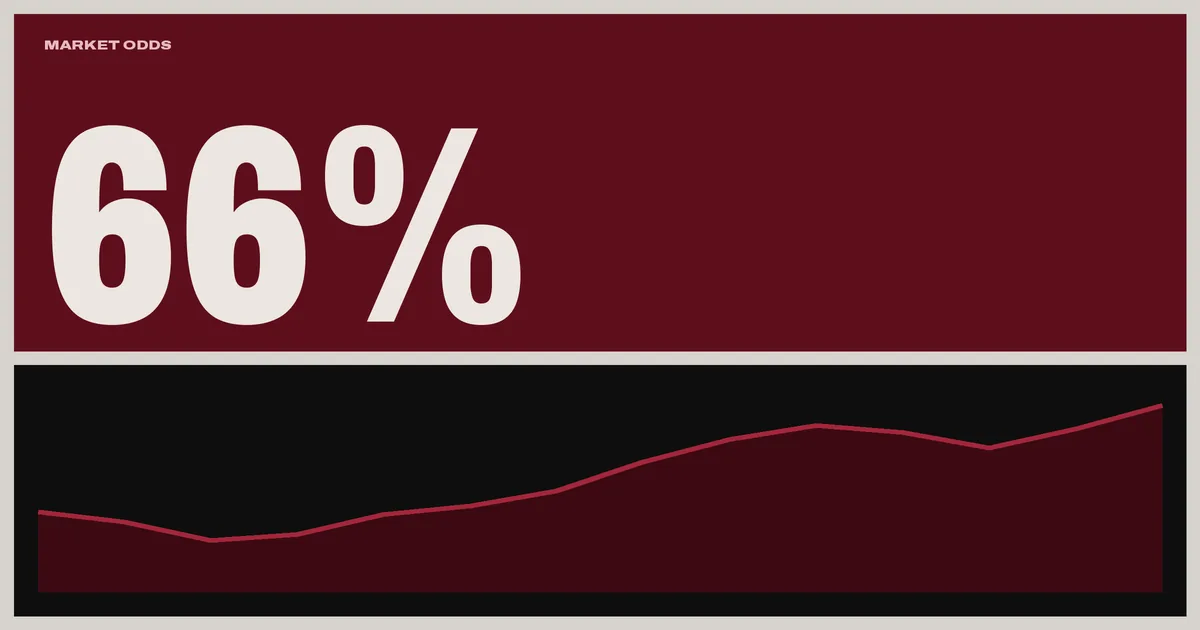
Rate-hike pricing for December is still the market's base case even after a violent equity session. Fed December 25 bps hike odds stayed near two-thirds on Polymarket as traders weighed a tech selloff against sticky inflation risk into year-end.
What happened
Polymarket's contract on whether the Fed will increase interest rates by 25 basis points after the December 2026 meeting showed Yes near 65.5% and No near 34.5%, with roughly $4.35 million in volume and about $638,000 in liquidity. The broader December decision event lists a matching no-change Yes near 34.5%, and the event window runs into early December 10 settlement framing.
CoinDesk's market wrap said CME FedWatch still priced a December hike near 69%, down from about 95% in late September, and flagged Friday's October jobs print plus next week's CPI as the path that could reopen a hold.
Why it matters
Prediction-market and futures pricing are converging on a hike even while risk assets de-lever. Our earlier Fed December 25 bps hike odds note already tracked elevated Yes pricing; the latest December hike tape shows that equity pain has not yet flipped the rates majority.
Cross-checks against other central banks matter for the dollar path. Coverage of the Bank of England November hike captured the UK's move to 4%; a Fed follow-through in December would keep the G10 tightening story alive into year-end rather than isolating the BoE.
Jobs and CPI are now binary for the hold minority: a soft labor print plus cooler inflation is the cleanest route to compress Yes pricing from the mid-60s toward a coin flip.
Liquidity near $638,000 on the Polymarket hike contract also means the odds can gap on a single data surprise without needing futures-scale notional to move.
Front-end Treasury and Fed funds futures will remain the institutional cross-check on Polymarket's two-thirds Yes pricing, especially if Friday's jobs print lands far from consensus. A soft labor surprise that compresses CME FedWatch toward 50% would likely pull the prediction-market hike contract lower even before CPI. Conversely, firm wages alongside sticky services inflation would give the December hike camp fresh ammunition into the blackout. Equity volatility alone has not been enough to flip the majority, which is the central lesson from Thursday's tape for rates traders. Options markets on Fed funds futures will remain the cleanest institutional cross-check if Polymarket liquidity thins around the data prints. Thin books on the prediction-market side can exaggerate moves relative to CME open interest on the same afternoon.
What's next
Watch the October employment report and the next CPI release for confirmation or compression of hike pricing. Polymarket's December Fed decision event is the primary source for Fed December 25 bps hike market odds.
A soft jobs surprise that pushes CME FedWatch below 50% would be the first serious challenge to the two-thirds Polymarket majority.
If both jobs and CPI stay firm, December hike pricing can grind higher even while Nasdaq volatility remains elevated.
The call
We say the Federal Reserve will increase the upper bound of the federal funds target range by 25 basis points at its December 2026 FOMC meeting. Polymarket priced Yes at 66% at 08:20 MSK on Nov. 6 on the December +25 bps contract. Equity volatility has cooled CME odds from September extremes, but majority pricing still treats a December hike as the base case into the meeting.
This article is for information only and is not investment advice. Calls are editorial forecasts, logged with market odds at the time of publication and kept on the record.